Boost Your Credit Before You Buy
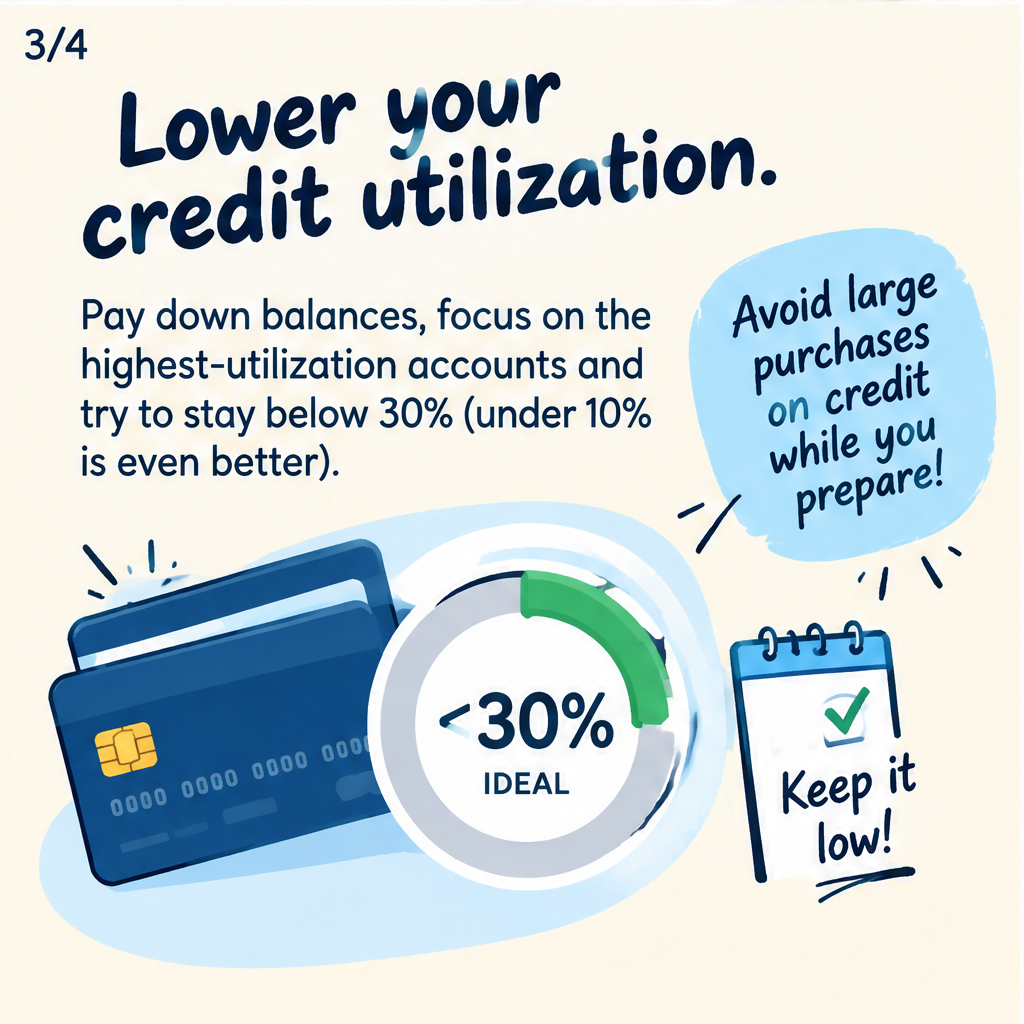
Before applying for a mortgage, give your credit profile time to improve. Start by checking both Equifax and TransUnion reports for incorrect balances, duplicate accounts, or outdated negative information. Dispute errors promptly and keep documentation of your requests. Credit utilization can significantly affect your score. Pay down credit cards and lines of credit, focusing first on accounts with the highest utilization. Try to stay below 30% of each limit, with under 10% being even stronger when practical. Avoid making large purchases on credit while preparing to apply. Payment history matters, so automate at least the minimum payment on every account and pay extra whenever possible. Avoid opening several new accounts, closing long-standing accounts without advice, or taking on unnecessary debt before your application. These habits can help create a steadier financial picture. Once your credit strategy is underway, speak with a qualified mortgage professional about your borrowing position and next steps. In Brampton’s active housing market, preparation can help you act with confidence when the right opportunity appears. A local real estate agent can also help align your budget with suitable homes and current market conditions.